The 5 Best Pool Financing Options for 2026: An Honest Ranking
Last updated: 2026-10-17
Turning a backyard into a private oasis is a massive undertaking. It often requires much more cash than most people have sitting in a savings account. Whether you are eyeing an inground pool, a luxury saltwater system, or a high-end swim spa, securing the right capital is the first step toward that summer splash.
The financial commitment extends far beyond the initial purchase price of the unit. You have to account for excavation, plumbing, electrical work, and the surrounding hardscaping required to make the area functional and beautiful. It is a long list of expenses that can add up quickly.
Selecting a lender is not a one-size-fits-all endeavor. What works for a homeowner with a pristine credit score might be a non-starter for someone recovering from a recent financial hiccup. A borrower with a 780 FICO score might find success with a traditional bank.
A borrower with a 620 score might need to look toward specialized lenders who prioritize stability and income over a perfect credit history. This ranking focuses on finding the most reliable paths to funding your aquatic dreams. We want to ensure you don’t settle for high-interest debt that hampers your long-term financial health.
- Avant
- FastLendGo
- HFS Financial
- Acorn Finance
- LightStream by Truist
How These Lenders Were Evaluated for Your Backyard Project
The selection process focused on accessibility and the specific needs of pool owners. A lender that specializes in general debt consolidation might not understand the nuances of a construction-heavy project. For instance, a pool installation is often a staged process.
You might pay a deposit to the contractor, a midpoint payment after excavation, and a final payment upon completion. Lenders that provide lump-sum loans are excellent, but those that can accommodate the workflow of a contractor are even better.
We looked at credit flexibility, the ease of the application process, and the specific loan products available. A lender that offers a quick decision is worth their weight in gold when a contractor is waiting to break ground. You don’t want to lose your spot on their schedule because of a slow bank.
We also analyzed the “soft pull” capability. This is the ability for you to check your potential rate without a hard inquiry that would lower your credit score. Every option was weighed against real-world usability, looking at how these companies handle everything from the initial inquiry to the final disbursement of funds.
Comparison of Leading Pool Financing Providers
| Lender Name | Loan Amounts | Interest Rates | Credit Requirements | Funding Speed |
|---|---|---|---|---|
| Avant | See site | See site | See site | See site |
| FastLendGo | $500 – $5,000+ | See site | Bad to Great Credit | See site |
| HFS Financial | $1,000 – $450,000 | From 7.80% | Bad Credit Options | See site |
| Acorn Finance | Up to $100,000 | From 6.99% | Good & Bad Credit | See site |
| LightStream by Truist | See site | See site | See site | See site |
Ranking the Top 5 Lenders for Pool Financing
1. Avant
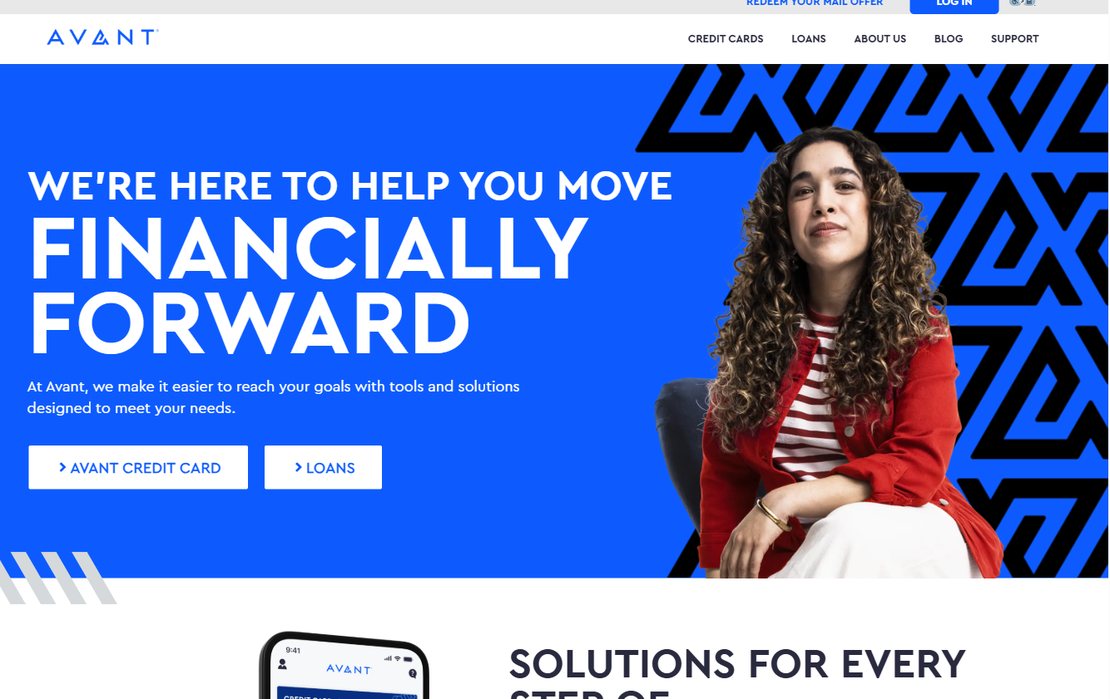
Avant positions itself as a versatile player in the personal loan market. They aim to help people move forward financially by offering flexible choices that fit into a variety of life stages. Their interface is designed for those who want to keep things simple and straightforward.
This makes it ideal for the tech-savvy homeowner who wants to manage their loan from a smartphone while standing in their newly renovated backyard. It is a modern approach for a modern renovation.
This lender is particularly useful for those needing to bridge the gap between a standard credit card and a massive mortgage. If you have a small pool project, such as a high-end hot tub or a sophisticated filtration system upgrade, Avant offers a way to get the funds without the lengthy paperwork required for a home equity line of credit (HELOC).
They offer solutions that can assist with home improvement or unexpected expenses. This makes them a solid choice for various backyard upgrades ranging from small fire pits to large stone walkways.
Pros:- Flexible loan solutions for different financial journeys.
- User-friendly online application process.
- Options for debt consolidation alongside home improvement.
- May not offer the specialized construction-focused terms found in niche lenders.
2. FastLendGo
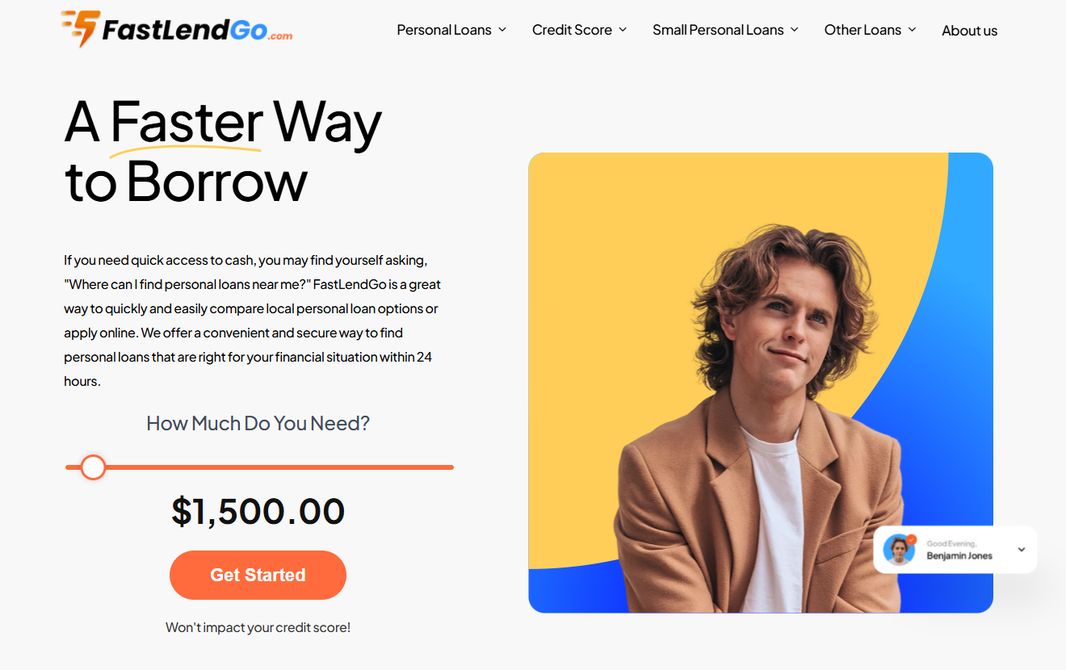
FastLendGo acts as a bridge for those who might feel sidelined by traditional banks. They specialize in a wide spectrum of credit profiles, ranging from those with bad credit to those with great credit. It is an excellent option for quick access to cash when you need to secure a seasonal discount from a pool professional or a supplier. (fastlendgo.com)
Whether you need a small $500 emergency loan for a broken pump part or a larger sum for a motorcycle or auto repair that you’d rather not pay for with a high-interest credit card, they cover the bases. They understand that life happens.
Their ability to compare local options makes them a highly efficient partner for those in a hurry to start a project. By looking at a wide array of lenders, they can often find a match for borrowers who might have been rejected by a local credit union.
Pros:- Extremely wide range of loan amounts.
- Caters specifically to bad and fair credit.
- Fast way to compare local financing options.
- Interest rates for bad credit may be significantly higher.
3. HFS Financial
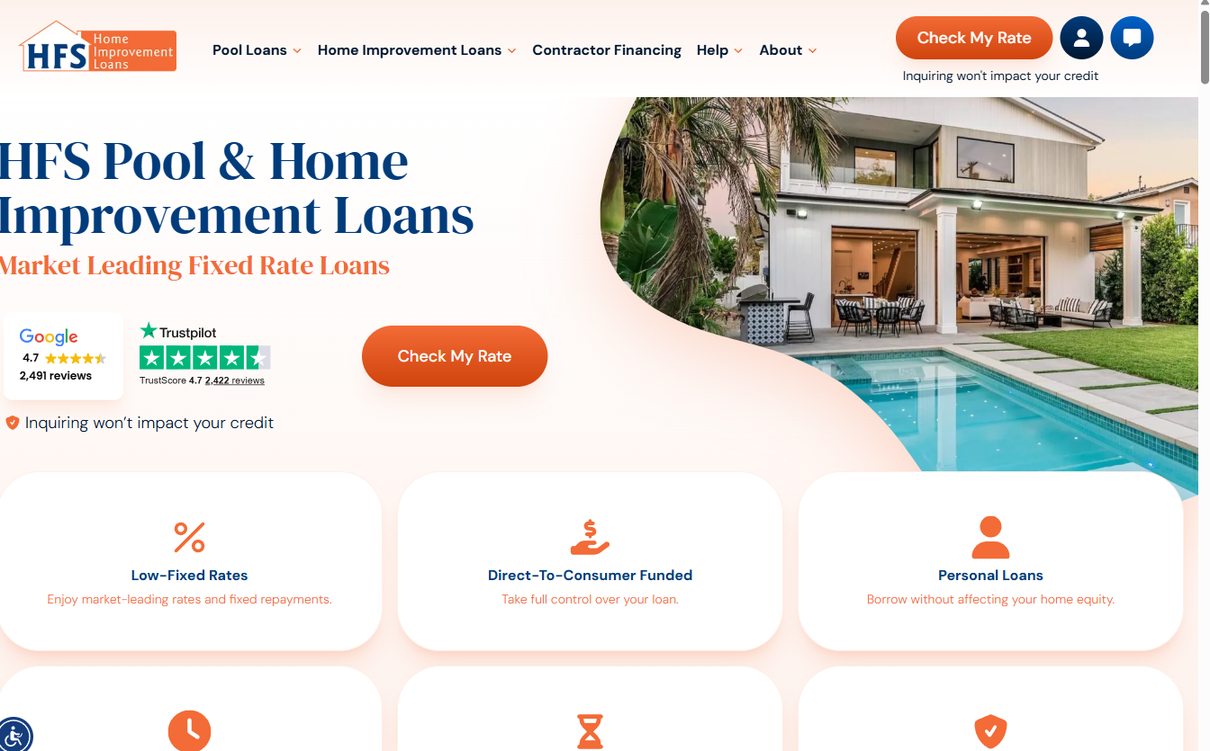
HFS Financial is a heavy hitter when it comes to specialized home improvement. They focus heavily on the actual assets being installed, such as swimming pools, hot tubs, or even solar panels. Unlike general personal loan lenders, HFS understands that a $50,000 pool is an investment in your property value.
Their limits are impressive, reaching up to $450,000 for major renovations. This could include a pool, a detached pool house, and extensive landscaping. It is a serious option for a serious project.
This is the go-to option for the homeowner who isn’t just buying a pool, but is undergoing a total backyard transformation. They understand the complexity of inground pools and luxury swim spas, offering rates that start at a competitive 7.80%.
They are well-versed in the “contractor-direct” model. In this setup, the lender often works closely with the professional performing the installation to ensure funds are released upon completion of specific project milestones.
Pros:- Massive loan amounts for large-scale projects.
- Specialized focus on pool and hardscape financing.
- Inquiring about rates does not impact credit scores.
- The high upper limits may require stringent documentation.
4. Acorn Finance
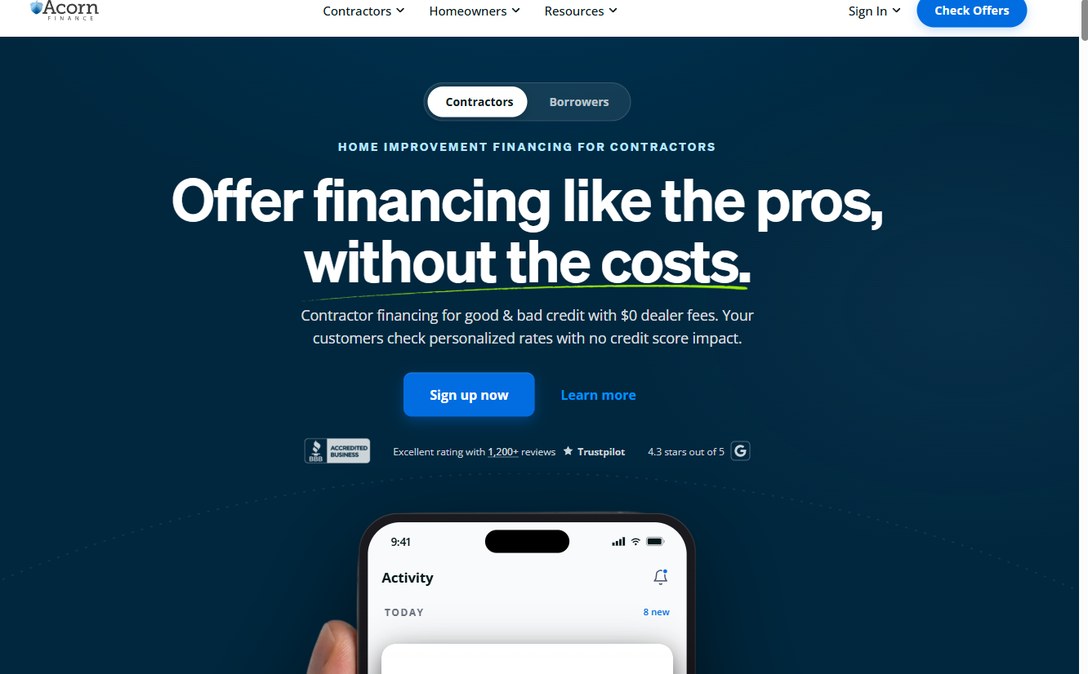
Acorn Finance operates with a unique model that connects borrowers with contractors. This is a 100% free service for both parties, which is a breath of fresh air in the lending world. They aim to provide clarity without the typical dealer fees that often get tacked onto the end of a contractor’s quote.
By using their marketplace, you aren’t just looking for money; you are looking for the right financial fit for your specific project scope. It is about finding the right tool for the job.
They offer a high level of convenience, allowing users to check personalized rates with no credit score impact. This is ideal for someone who is still in the “dreaming and planning” phase and wants to see what is possible before committing to a specific contractor or design.
You can run the numbers for a $20,000 concrete pool shell versus a $60,000 fiberglass shell to see how the monthly payments differ without any risk to your credit profile. It is a great way to test the waters.
Pros:- No dealer fees for the borrower.
- Personalized rates with no credit score impact.
- High user satisfaction based on extensive reviews.
- The marketplace model means you are dealing with multiple potential lenders.
5. LightStream by Truist
LightStream by Truist is a premier option for those who want to finance their pool without tapping into their home equity. It is a streamlined, digital-first approach designed to keep the focus on the improvement rather than the debt structure. It is a clean way to handle the math.
Because these are unsecured personal loans, you don’t have to worry about your home being collateral if the project runs over budget or if you face unexpected financial hardship. Your roof stays safe while you build your oasis.
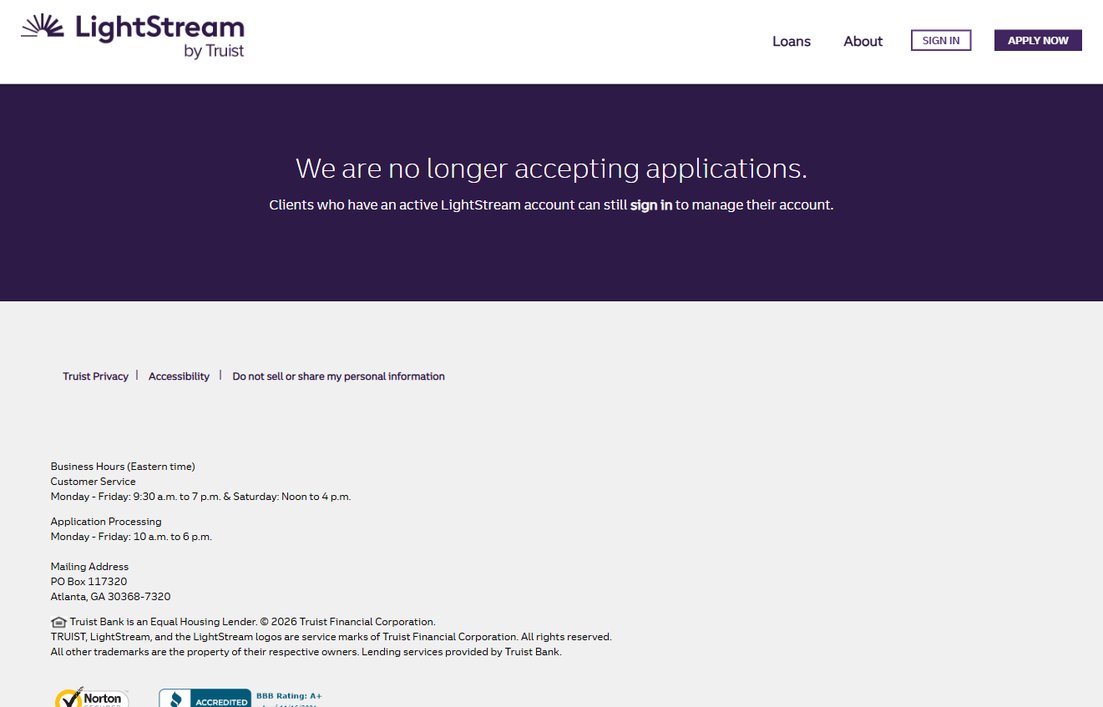
While they are currently not accepting new applications in some contexts, they remain a benchmark for how high-quality, fast-decision lending should look. For those with the right profile—typically high credit scores and steady, documented income—it is a seamless way to upgrade a home.
The speed of their approval process is often measured in hours rather than days. This makes it one of the fastest ways to move from “concept” to “construction.” You could be swimming by next month.
Pros:- Avoids the complexities of home equity loans.
- Fast and easy online application process.
- Backed by the stability of Truist.
- Availability of applications can be subject to change.
Understanding the True Cost of Pool Financing
Many homeowners make the mistake of focusing solely on the monthly payment. While a $150 monthly payment sounds much more manageable than a $600 payment, you must calculate the total interest paid over the life of the loan. It is a common trap.
For example, a $40,000 loan at 8% interest over 5 years results in significantly less total cost than the same loan over 10 years. If you can afford a higher monthly payment, you will save thousands of dollars in interest and build equity in your backyard much faster.
Consider these three common financial pitfalls in pool financing:
- The “Scope Creep” Trap: A project estimated at $30,000 often ends up costing $40,000 due to unexpected rock excavation, soil issues, or upgrades to the filtration system. Always borrow slightly more than the base quote to avoid needing a second, smaller, and more expensive loan later.
- The Interest Rate Trap: Don’t just look at the teaser rate. Check the APR (Annual Percentage Rate), which includes the interest plus any origination fees. A “low” interest rate with a 5% origination fee can actually be more expensive than a slightly higher interest rate with no fees.
- The Fixed vs. Variable Trap: Ensure you know if your rate is fixed for the life of the loan. Variable rates might start lower but can increase if market conditions shift, potentially making your “oasis” a financial burden during an economic downturn.
Preparing Your Documentation for a Fast Approval
To ensure your pool project moves from the planning stage to the construction stage without delay, you should gather your financial documentation before you even begin the application process. Lenders want to see a clear picture of your ability to repay the debt. Having these documents ready can shave days or even weeks off the approval process.
Prepare a digital folder containing the following:
- Proof of Income: Your two most recent pay stubs and your last two years of W-2 forms. If you are self-employed, have your most recent two years of tax returns ready, as lenders will look closely at your net income rather than gross revenue.
- Project Estimates: At least two detailed, written quotes from reputable pool contractors. Lenders like HFS Financial or Acorn Finance may require these to verify the intended use of the funds and the legitimacy of the project.
- Asset Statements: Recent statements for your checking and savings accounts. This demonstrates that you have the “cushion” necessary to handle the initial deposits and the ongoing maintenance costs of a pool.
- Identification and Residency: A valid driver’s license and recent utility bills to verify your address.
By approaching pool financing with the same level of organization as you would a mortgage, you position yourself as a low-risk borrower. This not only speeds up the funding process but often results in more favorable interest rates, ultimately saving you money on your backyard transformation.
Navigating Your Path to a Backyard Oasis
Before you sign on the dotted line, it is vital to look beyond just the interest rate. You must consider the total cost of borrowing. A low monthly payment might look enticing on paper, but a longer term can mean you pay thousands more in interest over the life of the loan. This is especially critical with large-scale projects like inground pools where the principal amount is substantial.
One common mistake is failing to account for the “hidden” costs of pool ownership. Installation is just the beginning; maintenance, chemicals, electricity for pumps, and potentially a specialized insurance rider are ongoing expenses. Ensure your loan amount covers the complete project, including the liner, the deck, the landscaping, and even the initial chemical startup kit.
Failing to budget for these can lead to a beautiful pool that remains empty because you cannot afford to run the pump. It is a heartbreaking sight for any homeowner.
Always check the fine print regarding prepayment penalties. If you come into a windfall—perhaps through a work bonus or the sale of an asset—and want to pay off your pool early, you don’t want to be hit with a fee for being responsible. Comparing these details between Avant, HFS Financial, and others will save you a massive headache down the road. A smart borrower looks for flexibility: the ability to pay extra toward the principal whenever possible without being penalized for it.